Many travelers think a winter travel insurance policy pays for any problem caused by snow. It does not. A policy may cover a weather delay but exclude a ski-racing injury, cover emergency treatment but not a planned medical visit, or pay for a canceled hotel only when the reason appears in the contract.
The reliable way to choose coverage is to match the policy wording to your trip. Check the medical limit, evacuation benefit, winter-sports rules, cancellation triggers, delay threshold, and pre-existing-condition language before paying. This guide uses U.S. policy examples. It does not interpret the insurance law of California, New York, Texas, or any other particular state; benefits, exclusions, and required notices can change by state of residence and by policy form. This is not legal advice — consult a licensed attorney.
Does a standard policy cover skiing and snowboarding?
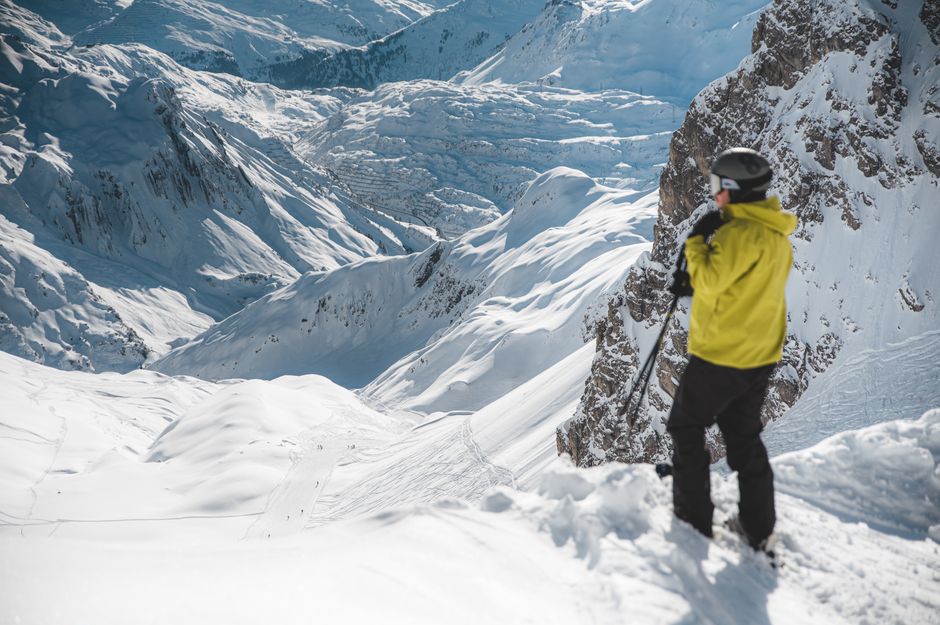
My verdict: buy winter-sports coverage only after reading the activity definition. A standard travel policy may treat skiing on marked, open resort runs as a covered recreational activity, yet exclude racing, professional training, terrain parks, off-piste travel, mountaineering, heli-skiing, or any run closed by the resort; the same word, skiing, can carry a narrow meaning in one contract and a broader meaning in another.
Ask where the activity happens
If your plan is a lift-served week at a named resort, check that ordinary downhill skiing and snowboarding are listed or not excluded, then confirm coverage while wearing the required helmet and following resort rules; if you plan backcountry travel, ski touring, snowmobiling, ice climbing, or a guided glacier route, look for an activity waiver that names that exact activity and does not quietly exclude avalanche terrain.
Ask what rescue means
Emergency evacuation may begin at a hospital, not at the place where you fell, and a resort patrol sled, helicopter, or mountain rescue team may be governed by a separate sublimit or excluded service, so the strongest winter plan is the one that states who authorizes rescue, what transport counts as medically necessary, and how the assistance company must be contacted.
Do not select a plan because a comparison page displays the word adventure. Keep a copy of the schedule of benefits, exclusions, and activity list with your booking records. For a high-risk itinerary, the policy with a smaller baggage benefit but a clear snow-sports waiver is the better choice.
How do health, pre-existing conditions, and evacuation fit together?
Travel insurance exists because ordinary health coverage and trip protection solve different problems. Your health plan may have an overseas network, deductible, or reimbursement process that does not work like care at home. Travel insurance may pay only for a sudden, unforeseen, medically necessary event and may require you to call an assistance center before arranging a transfer. The policy is not a replacement for routine care, prescription refills, preventive visits, or treatment undertaken mainly because the trip is convenient.
Read the pre-existing-condition definition
A pre-existing condition can include an illness, injury, symptom, diagnosis, or medication change during a stated look-back period. Some plans offer a waiver if you buy soon after the first trip payment, insure the full nonrefundable trip cost, and are medically able to travel when you buy the plan. Those conditions are strict. A traveler who waits until after a flare-up may lose the waiver even if the condition seemed stable earlier.
Separate treatment from transport
Emergency medical coverage pays for eligible care. Emergency transportation pays for a medically necessary transfer, which might mean moving you to a better-equipped hospital or returning you home after stabilization. Neither benefit automatically pays for a preferred hospital, a family member’s flight, a mountain rescue invoice, or an early return that a doctor did not approve. Check those details before departure.
Give the assistance provider usable facts
Save the insurer’s emergency number offline, carry your policy number, and keep a medication list with generic drug names. In a serious incident, ask the hospital to document the diagnosis, treatment, dates, and medical need for transport. Failure to follow a notice or authorization rule can create a claim dispute, although emergency conditions may change what notice was reasonably possible.
For U.S. travelers, state-specific policy forms matter. A plan sold to a Florida resident may not have identical wording or limits to the same branded plan sold to a resident of Illinois. Compare the certificate issued to your state, not a blog summary or another traveler’s screenshot.
What should you check before paying for the policy?
Use this five-minute policy audit
- List the money at risk. Add prepaid flights, lodging, lift tickets, equipment rentals, tours, and deposits that you cannot recover. Insure only the eligible nonrefundable amount and keep every receipt.
- Write down the winter activities. Record resort skiing, snowboarding, lessons, backcountry touring, snowmobiling, skating, or climbing. Match each activity to the policy’s covered-activity list.
- Test the weather language. Find the exact delay threshold, transportation shutdown requirement, resort-closure rule, daily expense cap, and receipt requirement. A forecast alone typically is not a covered loss.
- Check deadlines. Look for the purchase window for a pre-existing-condition waiver, cancel-for-any-reason option, work-related coverage, or financial-default protection. Missing the deadline can remove an important benefit.
- Save the evidence. Keep the policy certificate, exclusions, emergency number, booking confirmations, receipts, medical records, and carrier notices in cloud storage and on your phone.
The document that controls a claim
The sales page helps you compare plans, but the policy, schedule of benefits, endorsements, and state-specific terms control a claim. If a salesperson’s summary conflicts with the contract, ask the insurer for a written explanation before you buy. Do not assume that “covered for weather” means every storm-related loss is covered.
Which real plans are useful comparison points?
For a conventional family vacation with costly prepaid bookings, Allianz OneTrip Prime is the clearest starting point; for a plan with primary coverage and early-purchase features, Travelex Travel Select is stronger; for a longer, flexible trip where medical protection matters more than cancellation, SafetyWing Nomad Insurance Essential is the better comparison. None is automatically right for every traveler, and none should be purchased from the brand name alone.
Allianz OneTrip Prime
Allianz lists up to $100,000 for trip cancellation, up to $150,000 for trip interruption, $50,000 for emergency medical expenses, and $500,000 for emergency medical transportation. Its plan is designed for trips up to 180 days, and benefits vary by state. That makes it a strong fit for a family ski holiday with substantial prepaid costs, but the $50,000 medical limit deserves scrutiny for destinations with expensive care.
Travelex Travel Select
Travelex lists up to 100% of the insured trip cost for cancellation, 150% for interruption, $2,000 for trip delay, $50,000 for emergency medical expenses, and $500,000 for emergency evacuation and repatriation. A pre-existing-condition waiver may be available when the plan is purchased within 15 days of the initial trip payment, subject to the contract. Its winter-sports upgrade options should be checked for the exact activity.
SafetyWing Nomad Insurance Essential and World Nomads Explorer
SafetyWing’s Nomad Insurance Essential page lists a $250,000 overall limit, up to $100,000 for evacuation, and lost checked-luggage limits of $500 per item and $3,000 per policy. It is a medical-focused comparison point, not a direct substitute for a high-value trip-cancellation plan. World Nomads Explorer is another activity-focused comparison point, but its limits and covered activities vary by residence country and selected plan. Do not copy figures from a Canadian, Australian, or European quote into a U.S. purchase decision.
The final choice should follow the itinerary: for expensive prepaid resort bookings, prioritize cancellation and interruption; for remote terrain, prioritize medical, rescue, and evacuation wording; for a long flexible trip, check duration, renewals, home-country limits, and exclusions. The lowest premium is not the same as the lowest financial risk.